

A rigorous assessment of which business models will compound in the AI economy, which will be disrupted, and why the SaaS-pocalypse narrative – while partially right – misses the more important story
There is a widely circulated thesis in technology investing that AI will devastate the enterprise software industry by making many SaaS applications redundant. The logic is straightforward: if a general-purpose AI agent can perform the workflows that a specialized software application handles, then the application layer collapses. Investors have started calling this the ‘SaaS-pocalypse.’ It is a provocative thesis. It is also only about a quarter right.
The SaaS-pocalypse narrative captures something real: narrow, workflow-automation software that sits between a company and its own data – doing nothing more than helping users perform repetitive tasks within a single function – is genuinely at risk. An AI agent that can replicate those workflows at near-zero marginal cost is a direct substitute. If that is your entire value proposition, you have a problem.
But the thesis fails as a general prediction because it conflates two very different kinds of software business, and it systematically underestimates the durability of businesses whose value comes from places that AI cannot reach: proprietary data accumulated over years of transactions, end-customer relationships with deep trust and legal accountability, network effects that compound as participants grow, and the irreplaceable human judgment required to navigate genuinely complex decisions with high stakes.
Previous articles of this series built the mathematical tools for analyzing work, value delivery, and AI optimization at the firm level. We then applied those tools at the portfolio level – asking the investor’s question: which businesses will compound in an AI economy, and which will be pressured or displaced? The answer is more nuanced and more actionable than either the bulls or the bears on AI disruption have suggested.
I. The Correct Analytical Frame: Value Durability, Not Technology Disruption
The mistake most investors make when evaluating AI’s impact on a business is to ask a technology question: ‘Can AI do what this company does?’ That is the wrong question. The right question is an economic one: ‘Where does this company’s value come from, and is that source durable in an AI economy?’
The Mathematics of Value provides a framework to for answering this precisely. A business’s total value to its customers is the sum of eight components: functional output, outcomes, trust and relationships, speed, risk reduction, information and knowledge, network effects, and experience. AI changes the production cost and delivery speed of each component differently. The businesses that survive and compound are those whose dominant value components AI reinforces rather than substitutes.
The moat durability test can be formalized as a ratio:
The Moat Durability Ratio

Where
Key Insight
II. The SaaS Displacement Risk Index
Not all SaaS businesses are equally at risk. The degree of displacement risk depends on a precise combination of factors: how automatable the core workflow is, how easy it is for customers to switch, and how much of the product’s value is derived from data and network effects versus pure workflow execution. The Displacement Risk Index formalizes this assessment:
Definition
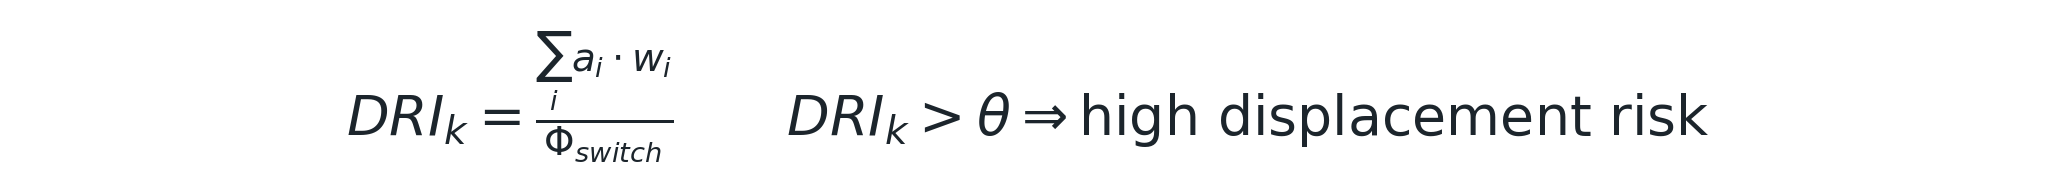
Where
The DRI framework reveals a critical insight that is frequently missed: a high degree of workflow automation (Σai·wi) is only fatal when switching cost is low. A product that handles a highly automatable workflow but holds years of proprietary, irreplaceable customer data is far more durable than its automation profile suggests. The data moat suppresses the denominator, keeping DRI below the displacement threshold even as AI improves.
III. The Businesses That Will Compound
The following analysis identifies the business model attributes that create durable competitive advantage in an AI economy. These are not simply ‘good businesses’ in the traditional sense – they are businesses whose specific structural characteristics make them more valuable, not less, as AI capabilities expand.
Category A: Proprietary Data Owners
The single most durable source of competitive advantage in an AI economy is owning a proprietary dataset that competitors cannot replicate. AI models are only as good as the data they are trained and grounded on. A business that has accumulated years of unique transactional, behavioral, or domain-specific data sits at the top of the value hierarchy, because its AI outputs will be structurally superior to any competitor’s – regardless of how capable the underlying model is.
The data moat compounds over time according to the following dynamic:
The Data Moat Value Equation
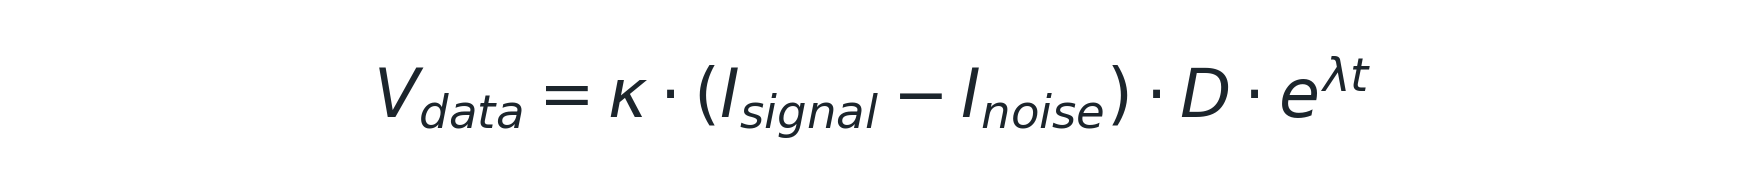
Where
- Examples of durable data moat businesses: Financial data aggregators with proprietary trading or behavioral data; clinical data platforms with longitudinal patient records; real estate databases with decades of transaction history; specialized insurance platforms with actuarial loss history; logistics networks with years of route and demand data.
- What to look for in due diligence: How many years of proprietary data does the company hold? Is it structured and annotated, or raw? Can it be replicated by a well-funded new entrant within five years? Is the data growing in volume and quality as a direct by-product of the company’s core operations?
Category B: Businesses That Generate Valuable Data as a By-Product of Their Core Service
A related but distinct category: businesses in which delivering the service continuously generates new proprietary data, and that data has value beyond the original transaction. These businesses are doubly advantaged in an AI economy: they use AI to improve service delivery (reducing cost and improving quality), and that improved service generates more data, which further improves the AI, in a virtuous loop that competitors cannot easily enter.
- The defining characteristic: The data is a natural exhaust of the transaction, not a separately harvested asset. It grows without friction as the business scales.
- Business model examples: Wealth management platforms where every portfolio decision and client interaction generates behavioral and outcome data; legal research platforms where every query and precedent search enriches the training corpus; healthcare diagnostics businesses where each scan or test result improves the model; supply chain platforms where every shipment generates route optimization and vendor reliability data.
- Investment implication: When evaluating these businesses, the most important question is not ‘what is the current revenue?’ but ‘how valuable is the data being generated, and what does it enable that competitors cannot replicate?’ The data asset may be worth more than the current business model captures.
Category C: End-Relationship Owners
There is a meaningful structural difference between businesses that own the customer relationship directly and businesses that serve other businesses that ultimately serve end customers. End-relationship owners – those with direct accountability to the end consumer or client, with trusted access to their most sensitive information and highest-stakes decisions – occupy a position that AI cannot displace. They are the locus of trust, accountability, and judgment.
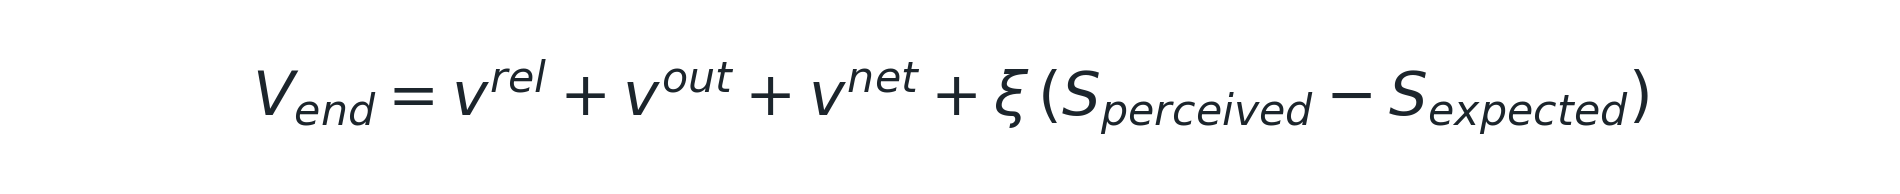
The relational value model is directly applicable here. End-relationship value is the composite of trust, alignment, and integrity – and these are multiplicative. A business that loses trust or alignment collapses its relational value to near-zero regardless of its functional capability. This makes end-relationship ownership one of the most durable competitive positions in any economy.
End-Relationship Value
- What end-relationship ownership looks like: Investment advisors and wealth managers with fiduciary accountability; primary care physicians and specialist networks with longitudinal patient relationships; tax and legal advisors with years of institutional knowledge about a specific client; commercial real estate advisors who know a client’s space needs, culture, and growth plans intimately.
- Why AI strengthens rather than displaces: AI augments the end-user by making them faster, better informed, and more proactive. It does not replace them because the customer’s willingness to act on a recommendation is grounded in trust in the specific human advisor, not trust in the AI model. The liability and the relationship both remain human.
- The vulnerability to watch: End-relationship owners who fail to adopt AI will be disadvantaged relative to those who do – not because AI replaces the relationship, but because AI-augmented advisors can serve more clients with better outcomes, thereby compressing the market share available to non-adopters.
Category D: Businesses Requiring Coordinated Judgment Across Complex, High-Stakes Decisions
The Mathematics of Work identifies σi – the judgment requirement – as the primary determinant of automation resistance at the task level. At the business model level, the equivalent concept is: businesses whose core value requires the simultaneous coordination of many high-σi tasks, where the interaction effects between decisions are complex, the stakes are high, and the accountability is legally or ethically non-delegable. These businesses are structurally insulated from AI substitution.
- Characteristics: Multiple interacting high-judgment decisions must be made in coordination, not in sequence. The error cost is high (legal liability, regulatory sanction, client harm). The context is specific to a particular client, case, or situation and resists generalization.
- Business model examples: Investment banking M&A advisory (legal, financial, regulatory, cultural, and strategic judgment must all be coordinated simultaneously); complex litigation (strategy, evidence assessment, client management, and negotiation all interact); institutional investment management where the client relationship, risk tolerance, tax situation, and market dynamics must be continuously balanced; crisis communications where reputation, legal exposure, and narrative must be managed in real time.
- Why AI strengthens rather than displaces: AI handles the JA component – research synthesis, document drafting, scenario modeling, data analysis – freeing the human judgment center to focus entirely on JH: the coordinated, high-stakes decisions that create the actual value. The result is a better outcome for clients at lower cost for the firm.
IV. Comprehensive Attribute Table: Businesses Positioned to Thrive
The following table consolidates the full set of business model attributes that create durable competitive advantage in an AI economy. These are the characteristics we look for in portfolio companies and acquisition targets.
V. The SaaS-Pocalypse: What It Gets Right
The displacement thesis is correct about a specific, large, and economically significant category of software businesses: those whose entire value proposition is helping users perform repetitive, bounded, function-specific tasks within a single business area – without owning meaningful data, without network effects, and without a direct relationship with the end customer they ultimately serve.
These businesses are not failing because AI is uniquely hostile to them. They are failing because they were always essentially workflow wrappers – products that abstracted the difficulty of a task without creating lasting economic value in the form of data, relationships, or network effects. The margin they captured was a tax on friction. AI eliminates the friction. The tax disappears.
VI. Comprehensive Attribute Table: Businesses That Will Struggle
The following attributes identify business models that face structural pressure as AI capabilities expand. This is not a prediction that every company in these categories will fail immediately — it is a prediction that their competitive moats are eroding and their valuation multiples will compress.
VII. The Investment Implication: Valuation Multiple Divergence
The most significant investment implication of the AI economy is not that some businesses will fail. It is that the valuation premium commanded by durable businesses will expand while the multiple assigned to at-risk businesses compresses – and that this divergence will happen faster and with more permanence than most investors currently anticipate.
The mathematical structure of this divergence is straightforward:
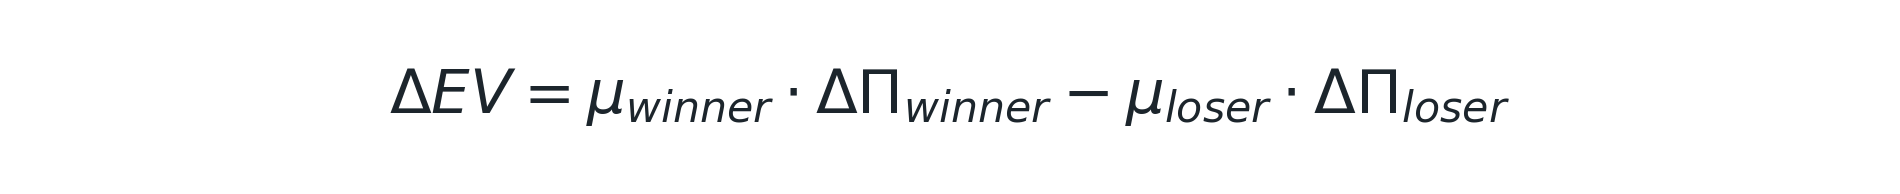
Where
For investors, the practical implication is a barbell portfolio strategy: overweight businesses with strong Mdurable scores (proprietary data, end-customer relationships, network effects, coordinated judgment requirements) and underweight businesses with high DRI scores (automatable workflows, no data lock-in, no end-customer relationship). The middle — businesses that are neither clearly durable nor clearly at risk – requires the most careful individual assessment.
One additional calibration: the timing of competitive pressure is not uniform. Businesses serving large enterprise customers with long procurement cycles and high switching costs will experience displacement pressure more slowly than businesses serving SMB customers who can switch in 30 days. The DRI score tells you the magnitude of risk; the customer profile and switching cost tell you the timing.
VIII. The BIP Capital Portfolio Thesis
At BIP Capital, the analytical framework described in this article directly informs how we evaluate businesses. We are looking for companies that score well on the durable attributes table and poorly on the displacement risk table. We are specifically seeking businesses that exhibit three or more of the following compounding characteristics simultaneously:
- A proprietary data asset that grows naturally as a by-product of operations, combined with a demonstrated ability to use that data to deliver customer outcomes that competitors cannot replicate.
- A direct, trusted, accountable relationship with the end customer, ideally in a regulated or high-liability context where the legal and ethical structure of the relationship preserves the human layer.
- Network effects that compound with participant growth and are curated — meaning the quality of participants matters, creating a judgment-dependent selection process that AI cannot automate away.
- AI adoption that is already underway and being used to expand the value proposition rather than simply reduce costs – businesses already executing the Model 3 (Value Chain Expansion) dynamic.
- A management team that understands the distinction between automation for margin and redeployment for growth, and that is explicitly managing the Lr / Lc allocation.
Conversely, we are cautious about businesses that have historically competed on workflow simplification, feature complexity, or integration management without building the underlying data and relationship assets that create lasting value. These businesses may be excellent operators with strong management teams – but they are fighting the AI tide rather than riding it.
Conclusion: A Measured Assessment
The SaaS-pocalypse is real, but it is not the whole story. It is the story of one specific category of business — narrow workflow automation without data ownership, network effects, or end-customer relationships — facing a structural substitution threat that compounds with each improvement in AI capability. For that category, the bears are right.
But for the broader universe of businesses that build genuine value through proprietary data, trusted customer relationships, curated networks, and the coordinated human judgment that high-stakes decisions require, AI is an amplifier, not a threat. These businesses will use AI to expand their value propositions, reduce their costs, and widen the gap between themselves and competitors who either lack the data assets to benefit fully or face displacement of their core workflows.
The investment opportunity in this transition is significant and time-sensitive. Valuation multiples have not yet fully diverged between these two categories. The businesses with the highest Mdurable scores — proprietary data owners, end-relationship holders, network-effect businesses, and coordinated judgment providers — are still being evaluated by many investors using frameworks built for a pre-AI economy. That mispricing will not persist. The analytical tools in this article series give investors the framework to identify and act on it before the market fully adjusts.
As always, we are interested in connecting with business leaders and investors who are rigorously thinking through these questions. The analysis gets better in conversation.