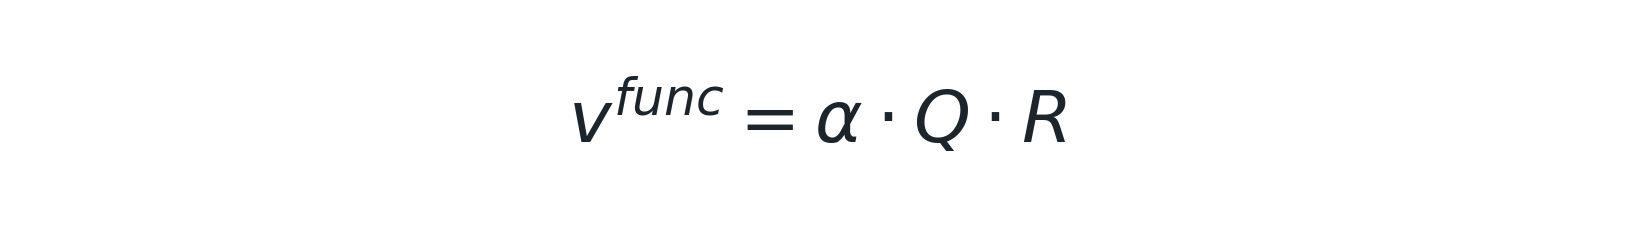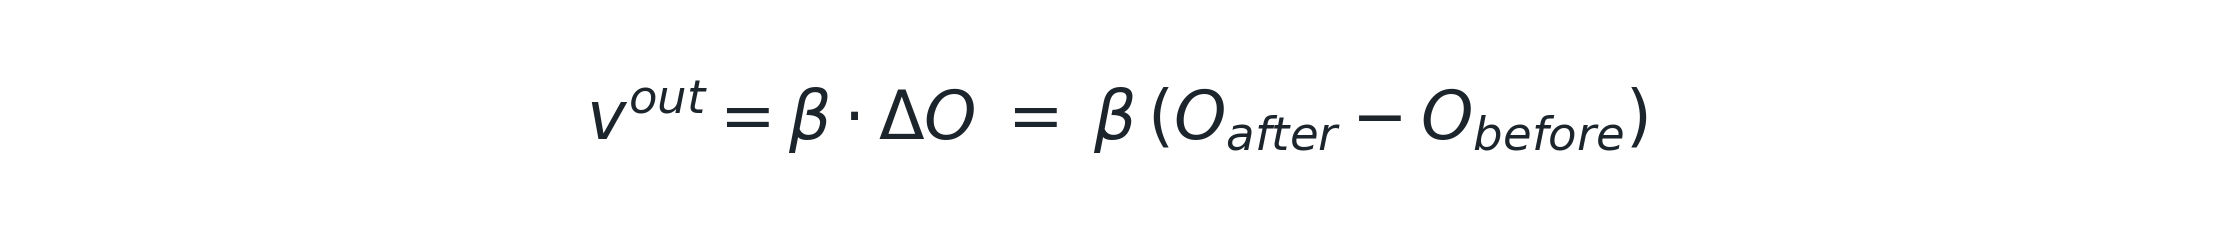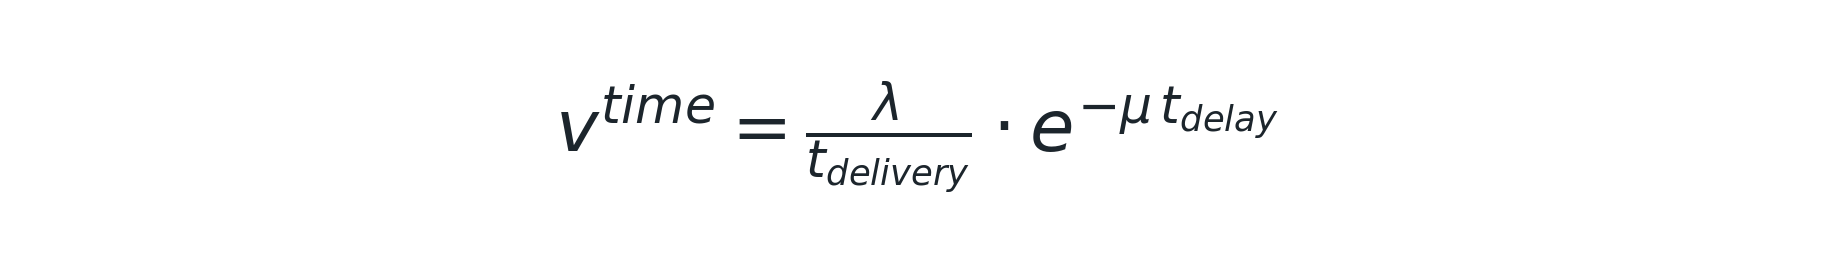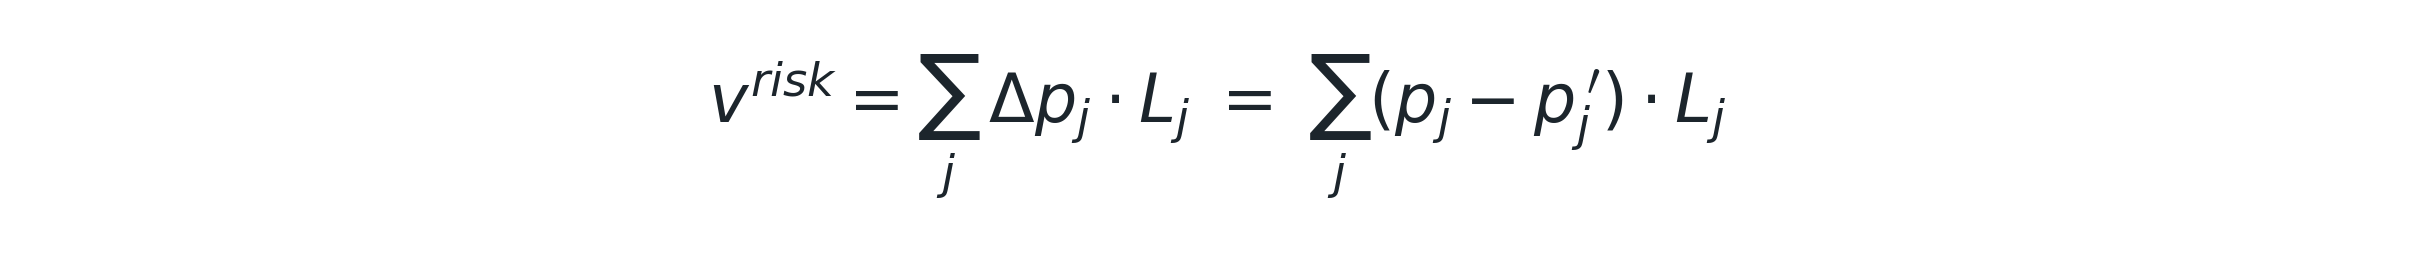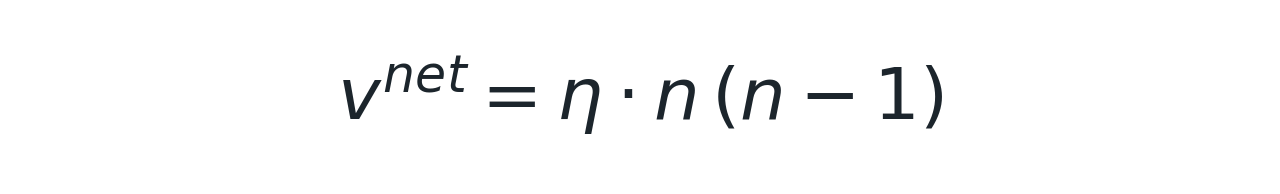A formal decomposition of the total value a company delivers to a customer — expressed in the same mathematical language as the Mathematics of Work.
First, we mathematized work – decomposing a job into its constituent tasks, assigning attributes of duration, cost, and cognitive effort, and modeling the degree to which each task is automatable. That framework gives us precision on the supply side of organizational economics: what work is performed, by whom or what, and at what cost.
The next article attacks the demand side with equal rigor: what a customer receives, how it should be decomposed, and how each component changes when AI is layered into the delivery system. Just as a job is not a single atomic act but a structured system of tasks, a value proposition is not a single benefit – it is a portfolio of distinct value types, each with its own drivers, decay rate, and leverage point.
Translating value into a mathematical framework provides several critical benefits. It enables precise measurement and comparison of what customers actually receive. It supports pricing strategy by connecting price to quantified benefit rather than input cost. It reveals where AI creates the most leverage. And it gives managers a common language for decisions about where to invest automation capacity, how to retain customers, and where expansion opportunities are most defensible.
“Just as a job is not a single atomic act but a structured system of tasks, a value proposition is not a single benefit — it is a portfolio of distinct value types, each with its own drivers, decay rate, and leverage point.”
The Master Equation: Total Value Delivered
We begin with the most important definition. The total value Vtotal that a firm delivers to a customer is the weighted sum of n distinct value components, net of the total friction cost Φ the customer must absorb to receive that value.
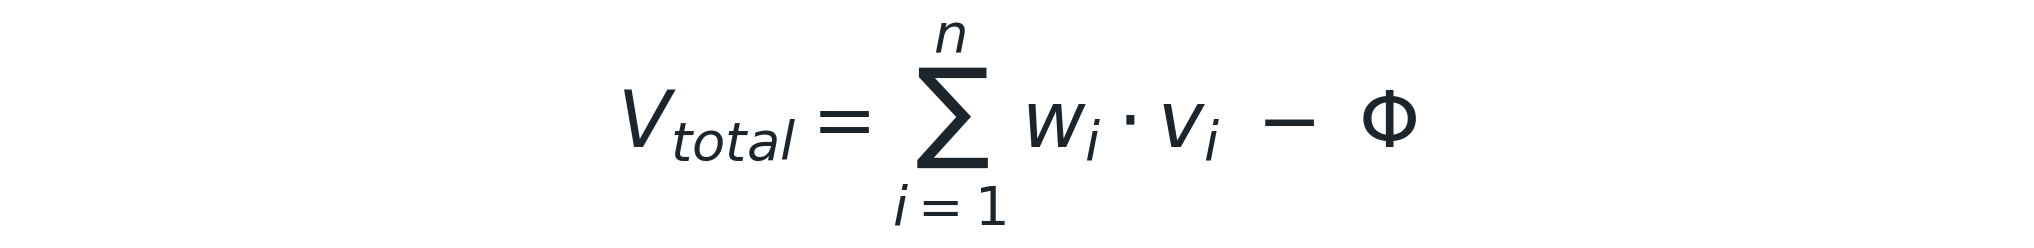
Where
Vtotal
Total Value Delivered
The aggregate value received by the customer across all value dimensions, after subtracting all friction costs. This is the number that governs whether a customer stays, expands, or churns.
n
Number of Value Components
The count of distinct value dimensions the firm delivers. For most businesses: functional output, outcomes, trust, speed, risk reduction, information, network access, and experience.
wi
Component Weight
The relative importance of value component i to this specific customer. Weights sum to 1. They vary by customer segment, buying context, and maturity. Understanding wi by segment is the foundation of value-based pricing.
vi
Component Value
The value of component i, which is itself a function of quality, reliability, timeliness, and cost-to-deliver. Each component has its own sub-model defined in the sections below.
Φ
Total Friction (Cost to Receive)
The sum of all costs the customer bears to receive the value: price paid, switching costs, learning costs, operational burden, and perceived risk. A firm can deliver high gross value and destroy net value if Φ is excessive.
Implication
Value is not a single number — it is a weighted portfolio. A firm that improves one component without understanding the customer’s weights risks optimizing for something the customer does not prioritize. AI changes both the vi terms (what is delivered) and the Φ term (how much friction the customer must bear to receive it).
1. Functional Value
Functional value is the most visible form: the direct output or deliverable that the customer contracted for. It is the result of the job being performed correctly. It is a multiplicative function of quality and reliability — both must be present for functional value to be high.
Definition
Let the functional value component be defined as:
Where
α
Functional Sensitivity Coefficient
How much this customer values each unit of quality and reliability. Higher for customers in regulated, high-stakes, or complex domains where errors have large downstream consequences.
Q
Quality
The degree to which the deliverable meets the agreed specification or industry benchmark. Measured on a 0–1 scale, where 1 represents perfect specification attainment. Analogous to the skill/effort attribute σ in the task model.
R
Reliability
The probability that the deliverable meets the quality standard consistently across all delivery instances. A firm that scores Q = 0.9 but R = 0.6 is a high-variance supplier — a significant source of hidden friction for the customer.
Implication
Q and R are multiplicative, not additive. A firm that delivers excellent work 80% of the time is mathematically less valuable than one that delivers good-to-excellent work 98% of the time when reliability is weighted heavily. Most firms track Q obsessively and under-manage R.
Organizational consequence
AI raises R toward 1.0 by reducing human-introduced variance. In professional services, this is often the primary source of AI-driven value improvement — not that the output gets dramatically better, but that it becomes consistently good.
2. Outcome Value
Outcome value captures whether the customer actually achieved the result they sought — not whether the deliverable was technically correct. It is the change in a measurable customer metric that is causally attributable to the firm’s work. This is what separates vendors from partners.
Definition
Let the outcome value component be defined as:
Where
β
Outcome Sensitivity Coefficient
The customer’s willingness to pay per unit of outcome improvement. Reflects how much a one-unit change in ΔO is worth to the customer in economic terms.
ΔO
Change in Outcome Metric
The measurable change in a customer outcome (e.g., revenue growth, cost reduction, time saved, defect rate, employee retention, risk-adjusted return) attributable to the firm’s work. Analogous to the output produced by the job in the task model.
Oafter
Outcome After Engagement
The value of the measured outcome metric following the firm’s engagement, product delivery, or service period.
Obefore
Outcome Before Engagement
The baseline value of the measured outcome metric prior to the firm’s involvement. Establishing this baseline at the start of an engagement is the single most important step in quantifying outcome value.
Implication
Firms that measure and communicate ΔO explicitly command premium pricing and structurally lower churn. Customers who can see the outcome improvement remain even when competitors offer lower prices, because switching means abandoning a proven ΔO track record.
Organizational consequence
AI accelerates outcome attribution by enabling near-real-time measurement of ΔO rather than waiting for contract renewal. Firms that instrument outcomes continuously convert a lagging retention indicator into a leading expansion signal.
3. Relational and Trust Value
Trust is not soft – it is an economically measurable component of value. Customers pay more, churn less, refer more, and absorb greater price increases in relationships where trust is high. Trust is a function of three compounding dimensions: documented track record, alignment of interests, and perceived integrity.
Definition
Let the relational value component be defined as:
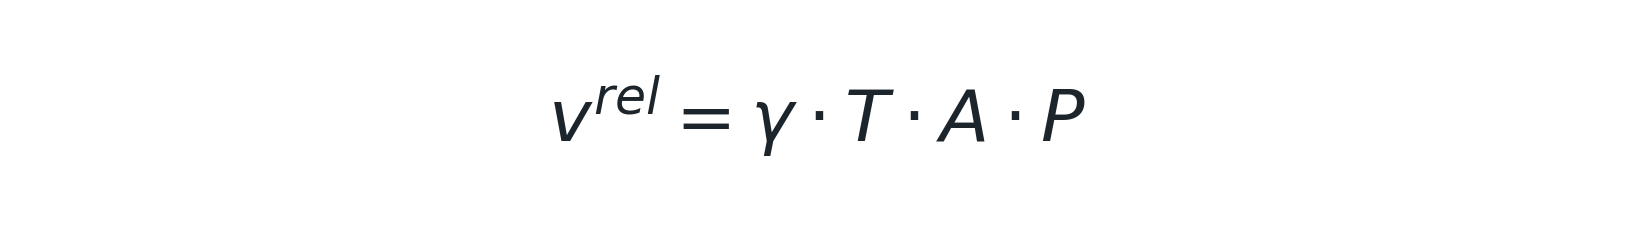
Where
γ
Relational Sensitivity
How much this customer weights trust relative to functional and outcome factors. Typically higher in long-cycle, high-stakes, or regulated relationships where the cost of a trust failure is catastrophic.
T
Track Record
The documented history of performance, delivery, and follow-through across prior engagements. Measured on a 0–1 scale. Directly analogous to the reliability term R in Equation 1, but evaluated across relationship cycles rather than individual deliveries.
A
Alignment of Interests
The degree to which the firm’s incentives, goals, and operating philosophy are perceived as congruent with the customer’s own. A firm that benefits when the customer benefits has structural alignment. A firm that benefits when the customer buys more, regardless of outcome, does not.
P
Integrity
The perceived ethical consistency, transparency, and accountability of the firm’s people and processes. Integrity failures are highly persistent in memory and disproportionately destructive to vrel.
Implication
T, A, and P are multiplicative. A score of zero on any single dimension collapses relational value entirely — a firm with an outstanding track record but perceived misalignment generates near-zero vrel regardless of its other scores. This is why client relationships do not recover from integrity failures.
Organizational consequence
AI-enabled transparency can strengthen T (by providing documented delivery records) and P (by making processes auditable and consistent). The risk is to A — if customers perceive automation as depersonalization or as a sign that the firm’s interests are drifting from theirs, relational value erodes even as functional output improves.
4. Speed and Time Value
Time has direct economic value. A customer who receives the same output faster can compound its benefit: moving faster to market, responding faster to competitive threats, or simply reducing the carrying cost of an unresolved problem. The speed value has two components: a positive return from fast delivery and an exponential penalty for delay.
Definition
Let the time value component be defined as:
Where
λ
Speed Sensitivity
The customer’s marginal value per unit of delivery speed. Higher in time-critical markets: financial services, media production, healthcare, and competitive intelligence. Lower in slow-cycle capital projects or long-horizon consulting.
tdelivery
Delivery Time
The actual time elapsed from engagement start to deliverable receipt. Appears in the denominator, so faster delivery generates more value, with diminishing returns at extreme speed. Analogous to the duration attribute δ in the task model.
μ
Delay Decay Constant
How rapidly value decays for each unit of time beyond the committed delivery date. High μ means the customer is severely punished by lateness — think a missed earnings filing or a time-sensitive acquisition bid. Low μ means lateness is tolerable.
tdelay
Elapsed Delay
Time beyond the committed delivery date. When tdelay = 0 (on-time delivery), e−μ·tdelay = 1 and no penalty is applied. As delay accumulates, the exponential decay term reduces vtime rapidly.
Implication
AI compresses tdelivery significantly across most service categories — analysis, drafting, synthesis, and reporting that took days now take hours. This does not just improve satisfaction; it mathematically expands vtime and creates value that did not previously exist at the prior delivery speed.
Organizational consequence
Speed improvement from AI is not purely an efficiency gain — it is a value creation mechanism. Firms that pass delivery-speed gains to customers as expanded capability rather than absorbing them as cost savings capture the value-creation narrative that drives premium positioning.
5. Risk Reduction Value
When a firm’s service reduces the probability or magnitude of a bad outcome for the customer, that reduction has direct economic value equal to the expected loss avoided. Risk reduction value is the expected loss before intervention minus the expected loss after intervention.
Definition
Let the risk reduction component be defined as:
Where
pj
Pre-Intervention Probability
Probability of adverse event j occurring before the firm’s service: a compliance failure, a security breach, a business disruption, a financial loss, a reputational event. This is the customer’s exposure without the firm.
pj′
Post-Intervention Probability
Probability of adverse event j occurring after the firm’s intervention. The gap pj − pj′ is the risk reduction achieved. Firms should measure and report this explicitly, not assume the customer perceives it.
Lj
Loss Magnitude
The economic, operational, or reputational magnitude of adverse event j if it occurs. Quantifying Lj in the customer’s terms — dollars of revenue at risk, regulatory fines, operational downtime — is essential to making risk reduction value tangible.
Δpj
Probability Reduction
The change in probability: pj − pj′. The larger this gap, the greater the risk reduction value. Summed across all relevant adverse events j, this is the firm’s total risk reduction contribution.
Implication
Risk reduction value is frequently underpriced because firms do not make Δpj · Lj explicit in client conversations. Firms that quantify the expected value of risks avoided – rather than listing services performed — consistently demonstrate a higher total value proposition and command fees commensurate with the protection they provide.
Organizational consequence
AI reduces pj by enabling better monitoring, early warning detection, compliance automation, and consistent process execution. The firms that will win the risk-reduction pricing argument are those that continuously instrument Δpj and surface it in client reporting.
6. Information and Knowledge Value
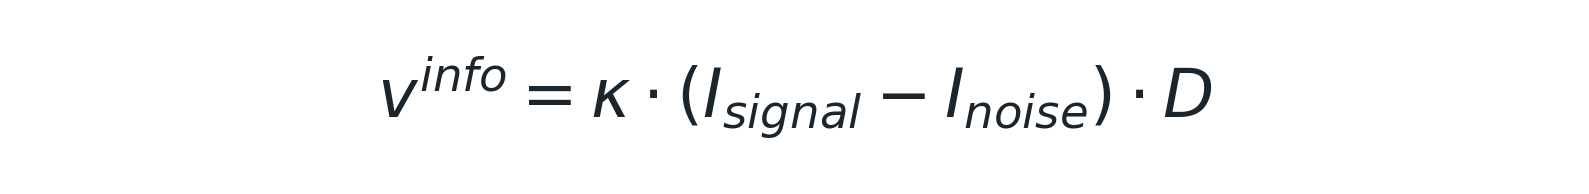
Firms that give customers better information — market intelligence, benchmarking, proprietary research, or decision frameworks — deliver value that is distinct from functional outputs. Information value is a function of signal quality, noise removal, and the degree to which the customer can act on what they receive.
Definition
Let the information value component be defined as:
Where
κ
Knowledge Sensitivity
How much this customer’s decisions are driven by information quality. Highest in investment, strategy, R&D, and competitive intelligence contexts. Lower in transactional or commodity relationships where decisions are price-driven.
Isignal
Signal Content
The quantity of actionable, decision-relevant information in the firm’s delivery. Signal does not mean volume — it means information that changes or improves a customer decision.
Inoise
Noise Content
Information volume that is irrelevant, redundant, or misleading. Noise reduces value even when signal is high — it consumes customer attention and can obscure the actionable content. This is analogous to waste in the task taxonomy.
D
Decision Leverage
The multiplier that converts insight into impact: the degree to which the information influences a customer's decision and its outcome. Information that informs but does not change behavior has D ≈ 0. Information that triggers a high-stakes decision has D >> 1.
Implication
AI dramatically expands Isignal by enabling synthesis, pattern recognition, and signal extraction at a scale no human team could match. But it also risks inflating Inoise if output is not curated. The highest-value AI applications in knowledge work are those that raise the signal-to-noise ratio, not just the volume of output.
Organizational consequence
Firms that deliver high-D information — insight that actually changes client behavior — create compounding loyalty. Clients who have made better decisions because of a firm’s information are structurally resistant to switching. AI that raises D, not just volume, is the differentiator.
7. Network and Ecosystem Value
Some firms deliver value not through their own direct outputs but through the access, connections, and network effects they provide. Following Metcalfe’s Law, the value of a network grows proportionally to the square of its connected participants. For platforms, ecosystems, and well-connected intermediaries, this component can dominate the total value proposition.
Definition
Let the network value component be defined as:
Where
η
Network Value Coefficient
The per-connection value to this customer, reflecting how much they benefit from each additional participant in the network. Higher when participants are highly curated, relevant, and accessible; lower in large but undifferentiated networks.
n
Active Network Participants
The number of accessible, active participants in the firm’s network or ecosystem who are potentially valuable to the customer: investors, co-investors, portfolio companies, advisors, clients, or partners. Not just total membership — activated participants.
n(n−1)
Total Directed Connections
The number of unique directed connections in a network of n participants. This is the functional form of Metcalfe’s Law and captures the compounding effect of network scale. Doubling n roughly quadruples the potential connection value.
Implication
Network value explains why platform businesses and well-connected intermediaries can outcompete larger, more isolated firms with superior direct capabilities. For investment managers, advisory firms, and professional service networks, vnet is often the primary reason a customer chooses one firm over another with equivalent technical quality.
Organizational consequence
AI can expand effective n by surfacing and activating latent connections that previously went unnoticed — pattern-matching clients to partners, opportunities to capabilities, and expertise to needs at a scale no human relationship manager could achieve manually.
8. Experience and Emotional Value
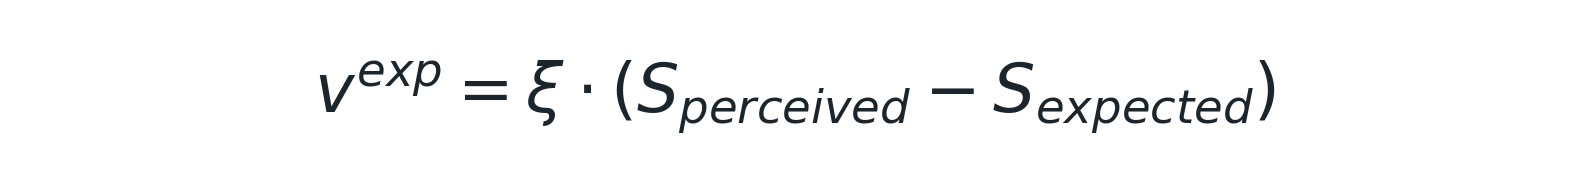
The final component captures something real but difficult to invoice: the quality of the customer’s experience of the relationship, independent of functional outputs. Customers who feel well-served, respected, and understood return at higher rates, refer more, and absorb occasional performance gaps. Experience value is the gap between perceived and expected service quality.
Definition
Let the experience value component be defined as:
Where
ξ
Experience Sensitivity
The degree to which this customer weights experience and relational factors in their overall valuation. Consumer relationships typically have higher ξ than B2B relationships, though high-stakes B2B engagements — M&A advisory, litigation, medical care — can be equally high.
Sperceived
Perceived Service Quality
The customer’s subjective assessment of how well the relationship, communication, responsiveness, and care were delivered. This is not the quality of the output (Q in Equation 1) — it is the quality of how the interaction felt.
Sexpected
Expected Service Quality
The baseline the customer arrived with, shaped by prior experience, peer benchmarks, competitor positioning, and the firm’s own marketing and commitments. Managing Sexpected is as important as improving Sperceived.
Implication
When Sperceived > Sexpected, the firm generates emotional surplus — the foundation of loyalty, referrals, and premium pricing power. When Sperceived < Sexpected, churn risk rises even when functional and outcome value remain intact.
Organizational consequence
AI that depersonalizes service interactions risks reducing Sperceived even while improving functional outputs. The firms that win in the AI era are those that use automation to remove friction from routine tasks – freeing human attention for the interactions that shape how a customer feels about the relationship.
9. The Friction Term: Φ
Every model of value delivery must account for the cost the customer bears to receive it. Φ is not the firm’s cost to produce the value — it is the customer’s total burden of acquisition and consumption. A firm can deliver high gross value and still destroy net value if Φ is excessive. Reducing Φ is as powerful a value creation lever as improving any individual vi component.
Definition
Let total friction be defined as:
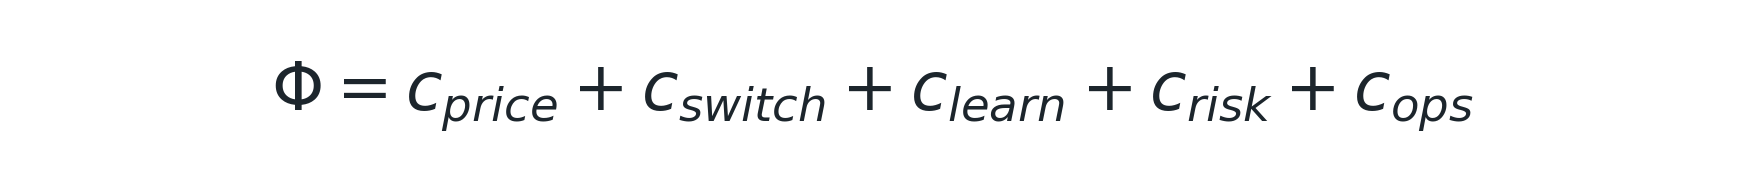
Where
cprice
Price
The direct monetary cost of the product or service. The most visible component of Φ, but in complex B2B relationships often not the largest. Customers who feel high Vtotal tolerate high cprice; those who cannot quantify Vtotal resist any price above a commodity reference point.
cswitch
Switching Cost
The economic and operational friction of moving from the current provider: data migration, retraining, contract penalties, relationship rebuilding, and performance risk during transition. High cswitch is both a retention mechanism and a market entry barrier.
clearn
Learning Cost
The time, effort, and distraction required for the customer to understand, configure, and become proficient with the firm’s offering. Often underestimated by firms that have optimized for their own workflow rather than the customer’s adoption experience.
crisk
Risk Cost
The customer’s risk-adjusted exposure to failure or underperformance by the firm. This is distinct from vrisk: risk cost is a friction the customer bears upfront regardless of outcome; risk reduction value is the benefit received when the firm actually reduces the probability of a bad event.
cops
Operational Burden
The ongoing administrative, coordination, and management overhead the customer must absorb to work with the firm: reporting requirements, meeting cadence, approval workflows, and integration complexity. Often the most underestimated component of Φ in professional service relationships.
Implication
Reducing Φ creates value that is fully attributable to the firm without requiring any improvement in the underlying delivery. A firm that cuts cops in half while holding all vi constant has materially improved Vnet for every customer.
Organizational consequence
AI reduces Φ significantly on three dimensions: clearn through better onboarding and intelligent support; cops through automated reporting, status, and coordination; and crisk through greater delivery reliability. These reductions directly increase Vnet without requiring any improvement in gross value components.
10. Net Customer Value and the Retention Condition
The master equation resolves to a single condition that governs whether a customer stays, expands, or churns. Net customer value Vnet is the difference between total value delivered and total friction absorbed.
Definition
This condition maps directly to observable customer behavior:
- Vnet > 0 and rising → Customer expands the relationship, refers peers, and advocates. Pricing power is high.
- Vnet > 0 and flat → Customer renews but does not grow. Vulnerable to a competitor who offers a credible improvement in any weighted component.
- Vnet ≈ 0 → Customer is at structural churn risk. A single friction event or competitive offer tips the balance.
- Vnet < 0 → Churn is economically rational for the customer and will occur as soon as switching cost is overcome.
Implication
Most firms price and manage retention as though Vnet is uniform across their customer base. It is not. Because wi weights and Φ differ materially by segment, size, and maturity, net value is highly heterogeneous at the same price point. Firms that model Vnet at the customer level gain a structural advantage in churn prediction, upsell timing, and pricing strategy.
Strategic consequence
The retention condition is also the acquisition condition. A customer considering a switch compares Vnet(new) against Vnet(current) + cswitch. Winning new customers requires not just delivering superior value but also generating enough surplus to overcome the switching-cost friction embedded in the incumbent relationship.
11. AI-Augmented Value: The Expanded Master Equation
The framework above describes value delivery in a human-only or legacy-technology context. When AI is layered into the delivery system, the master equation expands. AI does not simply make existing components larger – it adds new value dimensions that were previously inaccessible and reduces friction simultaneously. But it also introduces a temporary transition cost that must be modeled honestly.
Definition
Let the AI-augmented total value be defined as:

Where
VAItotal
AI-Augmented Total Value
Total value delivered in an AI-augmented model. This is the new master equation for organizations that have completed meaningful AI transformation. It governs the value competition in the post-transition competitive environment.
Vtotal
Baseline Total Value
The total value delivered before AI augmentation — all eight components from Sections 1–8 at their pre-AI levels, net of pre-AI friction. The starting point for measuring the AI dividend.
Δvspeed
Speed Uplift
Incremental value from delivery speed improvement. AI reduces tdelivery and tdelay across most service categories, directly expanding vtime and Δvspeed.
Δvscope
Scope Expansion
Incremental value from delivering components or sub-components that were previously economically infeasible without AI. Connects directly to Model 3 (Value Chain Expansion) from the article: AI moves the value frontier outward.
Δvinsight
Insight Quality Uplift
Incremental value from improved information quality: AI raises Isignal and the signal-to-noise ratio, expanding vinfo and improving the D (decision leverage) multiplier.
ΔΦtransition
Transition Friction Cost
The temporary increase in Φ the customer bears during AI adoption: workflow disruption, retraining, adjustment period, and trust calibration. This cost is real, time-bounded, and must be explicitly managed. It is the primary reason AI transformations stall at the customer experience layer even when internal efficiency gains are real.
“The AI dividend is not automatic. It equals Δvspeed + Δvscope + Δvinsight minus ΔΦtransition. Organizations that invest in transition management shrink ΔΦtransition and capture the full uplift faster. Those that underinvest leave the dividend on the table while still paying the transition cost.”
12. Summary: The Value Decomposition at a Glance
The table below summarizes all eight value components, their primary drivers, and how AI affects each dimension. Use this as a diagnostic: for each component, assess your current level of delivery, the weight your target customers assign to it, and the degree to which AI investment can expand it.
| Component | Value Type | Primary Drivers | How AI Changes It |
|---|
| vfunc | Functional | Quality (Q) × Reliability (R) | Raises R toward 1.0 — consistency is the primary functional gain from AI |
| vout | Outcome | Measurable ΔO attributed to the firm | Enables real-time ΔO measurement; converts lagging to leading indicator |
| vrel | Relational/Trust | Track record × Alignment × Integrity | Strengthens T and P; risks A if automation feels depersonalizing |
| vtime | Speed/Time | 1 / tdelivery × e−μ·tdelay | Primary driver of speed compression across all service categories |
| vrisk | Risk Reduction | Σ Δpj × Lj across all adverse events j | Reduces pj via monitoring, compliance automation, and process consistency |
| vinfo | Information | (Isignal − Inoise) × Decision leverage D | Expands Isignal; critical risk is inflating Inoise without curation |
| vnet | Network | η × n(n−1) connections | Surfaces latent connections; effectively expands active n |
| vexp | Experience | Sperceived − Sexpected | Risk: raises functional quality while reducing perceived warmth |
| Φ | Total Friction | cprice + cswitch + clearn + crisk + cops | Reduces clearn, cops, and crisk — net friction falls materially over time |
13. What This Framework Changes
The Mathematics of Value is not a theoretical decoration. Like the Mathematics of Work article, it is a practical tool for managers, strategists, and investors. When applied rigorously, it changes four things:
- How you price. Firms that quantify Vnet at the customer level price on delivered value rather than input cost — capturing more margin in high-weight relationships and reducing churn-driving over-pricing in low-weight segments.
- How you allocate AI investment. The equation identifies which value components carry the highest wi for your target customers, revealing where AI-driven improvement creates the most leverage and where it is marginal.
- How you retain customers. Vnet modeled at the individual customer level converts retention management from intuition-driven relationship maintenance into an analytically grounded early-warning system.
- How you tell your story. Firms that can quantify ΔO, Δpj · Lj, and net Vnet in client conversations are fundamentally more persuasive than those who list activities performed. The math transforms anecdotal claims into evidence-based arguments.
The next article will bring the Mathematics of Work and the Mathematics of Value together – modeling the intersection between how work is performed, how value is delivered, and where AI creates the most powerful leverage across both dimensions simultaneously.
© BIP Capital • This article reflects the views of BIP Capital’s Investment and Performance Engineering Team. It is intended for informational purposes and does not constitute investment advice.