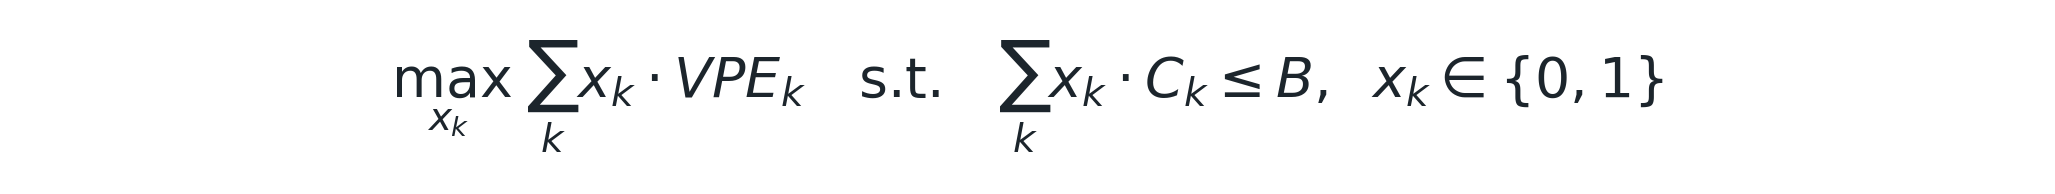A step-by-step framework for cataloguing tasks, identifying value expansion opportunities, and deploying the mathematical models that maximize AI’s impact on firm performance
Most business leaders understand, in principle, that AI represents a significant opportunity. Fewer know where to begin. The gap between conviction and action is not usually a lack of tools or budget — it is a lack of a systematic process for translating AI’s general promise into specific, measurable, and sequenced decisions about their own business.
The earlier articles in this series laid the mathematical foundations: introducing the Mathematics of Work, a formal framework for decomposing any job into its constituent tasks and modeling the degree to which each is automatable. Next, we learned the Mathematics of Value, a framework for decomposing what a business delivers to a customer into eight distinct value components, each with its own drivers, decay rates, and AI leverage points. This article puts both frameworks into motion. It is a practical roadmap — eight sequential steps that take a business leader from a blank page to a fully specified, mathematically grounded AI optimization strategy.
The roadmap is deliberately sequential. Step 1 cannot be skipped to reach Step 5 any faster than a building can skip its foundation to reach the roof. Each step produces an output that the next step requires. And the mathematical models at each stage are not decoration — they are the tools that convert qualitative assessments into defensible, comparable, and actionable numbers.
“There is a difference between knowing that AI can transform your business and knowing which tasks to automate first, which value components to expand, how to allocate freed capacity, and how to measure whether it is working. This roadmap closes that gap.”
Phase 1: Build the Task Inventory
Map Every Task in Every Job
Before any optimization is possible, you need a complete accounting of the work your organization performs. This is the task inventory — the raw material from which every subsequent decision will be built.
The most common mistake business leaders make at the start of an AI initiative is to think in terms of jobs and roles rather than tasks. They ask, ‘which jobs could be automated?’ when they should be asking ‘which tasks, within which jobs, should move along the automation spectrum – and in what order?’ The Mathematics of Work is explicit about why: a job is not an atomic unit; it is a structured system of tasks. The automation decision lives at the task level, not the job level.
Building the task inventory requires a structured approach. For each function, team, or business unit, the goal is a complete register of tasks – what work is being performed, by whom, how often, and at what cost. Operationally, this is best accomplished through a combination of manager interviews, workflow documentation reviews, time-tracking data analysis, and structured self-reporting by individual contributors. The output should be a task register formatted as a spreadsheet with the following columns:
Task Register Structure
- Task Name and Description: A clear, specific description of the task. Not ‘analysis’ but ‘compile weekly revenue variance report from three data sources and distribute to leadership.’
- Function / Role Owner: Which team performs this task, and at what level in the organization.
- Frequency: How often the task recurs – daily, weekly, monthly, per client, per transaction, ad hoc.
- Duration (δi): Average time in hours per instance. Multiply by frequency and team size to get weekly task hours.
- Fully Loaded Cost (ci): Labor cost per year for this task across all performers: (FTE fraction) × (loaded salary + overhead). This is the financial exposure if the task is not optimized.
- Judgment Level (σi): A 0–1 score representing the cognitive and judgment requirement. See the scoring guide below.
- Repeatability (ri): A 0–1 score representing how standardized and repeatable the task is across instances.
- Current AI Involvement: What, if any, AI or automation is already being applied to this task today.
Key Insight
A typical mid-sized professional services firm will identify between 80 and 200 distinct tasks when this exercise is done rigorously. Most leadership teams are surprised by how many high-cost, low-judgment tasks exist in their organizations — tasks that have been performed by skilled humans simply because no one had mapped them explicitly or asked whether they needed to be.
Phase 2: Score and Rank Automation Opportunities
Compute the Task Value Score (Si) for Every Task
With the task register complete, the next step is to score each task on its automation priority. The Task Value Score produces a single, comparable number for every task — enabling leadership to rank automation opportunities objectively rather than politically.
The Task Value Score Equation
The Task Value Score Si measures how much value a task would generate if automated — balancing how automatable it is against how much cost and time it consumes:
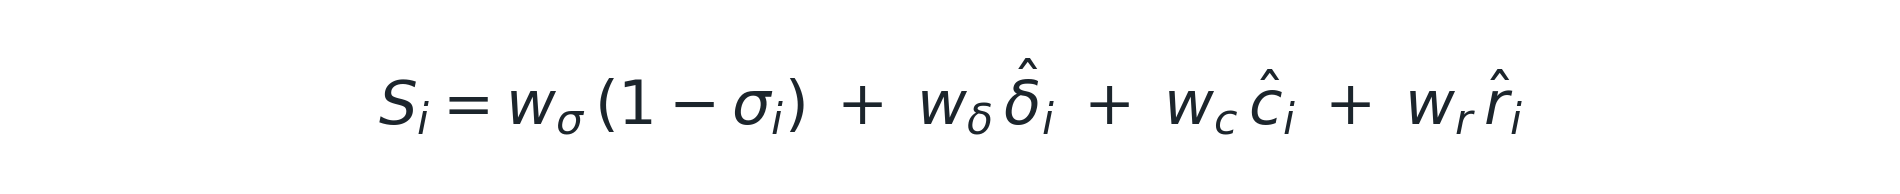
Where
Si
Task Value Score
A composite priority score for automating task i. Higher scores indicate tasks where automation yields the greatest organizational benefit. Scores are normalized and comparable across all tasks in the register.
wσ
Judgment Weight
The weight assigned to the judgment dimension in the composite score. Recommended default: 0.35. Low-judgment tasks (σi near 0) score highest on this dimension, signaling strong automation candidacy.
(1-σi)
Automation Eligibility
The inverse of the judgment score. A task with σi = 0.1 scores 0.9 on this dimension — highly automatable. A task with σi = 0.9 scores 0.1 — strongly human-required.
wδ, δ̂i
Duration Weight & Normalized Duration
Weight on the time dimension (recommended: 0.25) times the task’s normalized duration (task δi divided by max δ in the register). High-δ tasks represent the most significant time liberation opportunity.
wc, ĉi
Cost Weight & Normalized Cost
Weight on the cost dimension (recommended: 0.25) times the task’s normalized fully loaded cost. High-c tasks deliver the most direct margin improvement when automated.
wr, r̂i
Repeatability Weight & Normalized Repeatability
Weight on the repeatability dimension (recommended: 0.15) times the normalized repeatability score. High-repeatability tasks generate compounding ROI because automation benefits multiply with every occurrence.
Scoring Guide for σi and ri
| DIMENSION | WHAT TO MEASURE | HOW TO SCORE |
|---|
| σi — Judgment Level | Does this task require contextual reasoning, client judgment, ethical discretion, or novel problem-solving? | Low judgment (0.0–0.3): automate first Med judgment (0.3–0.7): copilot candidate High judgment (0.7–1.0): keep human |
| δi — Time Consumed | How many hours per week does the average performer spend on this task across the team? | Normalize to 0–1 scale across all tasks. High-δ tasks represent the largest time liberation potential. |
| ci — Fully Loaded Cost | What is the total labor + overhead cost of this task per year? (FTE fraction × loaded salary + tools) | Normalize to 0–1 scale. High-c tasks deliver the most direct margin improvement when automated. |
| ri — Repeatability | How often does this task repeat in identical or near-identical form? (daily, weekly, per client, per transaction) | High repeatability = high ri. Automation ROI compounds with volume. One-off tasks score low. |
Key Insight
The Si equation is not a black box – it is a transparent weighting framework that leadership teams can adjust to reflect their own priorities. A firm under acute margin pressure might increase wc. A firm trying to accelerate delivery might increase wδ. The weights are inputs to be debated, not constants to be accepted.
Phase 2 output
A ranked list of all tasks in the register, sorted by Si score from highest to lowest by function. The top quartile of this list is your automation roadmap. Tasks in the top decile should be piloted within 90 days.
Phase 3: Partition Tasks and Calculate Total Automation Opportunity Value
Divide the Task Register into TA and TH — Then Quantify What’s at Stake
The Si ranking tells you which tasks to automate first. The partition model tells you what the total prize is. Before committing to an automation program, leadership should know the full financial and capacity value of moving the highest-scoring tasks from the human-required set into the automatable set.
Using the Si scores and the judgment levels (σi) from Phase 2, define a threshold score S* above which tasks are designated as automation candidates TA*. Tasks below the threshold remain in TH for the current planning cycle. This partition is not permanent — it should be revisited every quarter as AI capabilities evolve and as the organization builds implementation capacity.
Total Automation Opportunity Value
The Automation Opportunity Value (AOV) quantifies the financial value of moving all tasks in TA* from human to machine execution:
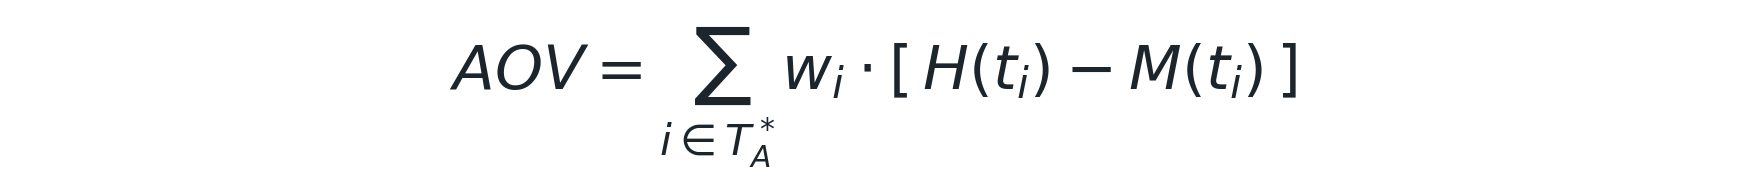
Where
AOV
Automation Opportunity Value
The total economic value available from automating all tasks in the priority set TA*. Measured in dollars per year. This is the upper bound on cost savings and capacity liberation from automation — the actual realized value will depend on implementation quality and speed.
wi
Task Importance Weight
The strategic importance of task i in the job’s overall output (from the weighted task model). This ensures the AOV calculation reflects business impact, not just cost, by weighting high-importance tasks more heavily.
H(ti)
Human Execution Cost/Value
The fully loaded annual cost of human execution of task i.e. In most professional service contexts, this is (FTE fraction × loaded salary × frequency). This is what you are paying for today.
M(ti)
Machine Execution Cost/Value
The estimated annual cost of AI or automated execution of task i: model inference costs, workflow tooling, and oversight time. For most text, data, and analysis tasks, M(ti) is 5–15% of H(ti) at scale.
H-M
Automation Economic Surplus
The annual value released per task when it moves from human to machine execution. Summed across TA*, this is the total automation dividend available to the firm — to be allocated between margin improvement and growth redeployment.
Key Insight
AOV is not a cost-savings target – it is a capacity-liberation budget. The fundamental strategic question is not how much of AOV to take as cost reduction, but how to allocate it between the Expense Index and the Revenue Index. That allocation decision is the subject of Phase 6.
Phase 3 output
A financial model showing AOV by function, total firm AOV, and the Si-ranked 90-day automation pilot list. This is the business case document for the automation program. Present it alongside the partition map showing TA vs. TH for each job in the register.
Phase 4: Catalog Value Proposition Expansion Opportunities
Identify Every Way AI Can Expand What You Deliver to Customers
The automation work in Phases 1–3 addresses the supply side: how work gets done. Phase 4 attacks the demand side: what value you deliver. Mathematics of Value gives us eight distinct value components. For each one, leadership must ask: where can AI enable us to deliver something we could not deliver before, or deliver it at a quality or speed that creates new competitive separation?
Value Proposition Expansion (VPE) is not the same as service addition. Most organizations already offer a wide range of services. VPE is about identifying the specific value components – functional, outcome, relational, speed, risk reduction, information, network, and experience – where AI creates a step-change in what is possible. The test is simple: would this offering have been economically infeasible or operationally impossible without AI? If yes, it is a genuine VPE opportunity. If it is simply making an existing service marginally better, it is an efficiency gain, not an expansion.
The VPE cataloging process is best run as a structured working session with functional leaders, using the eight value components as the organizing framework. For each component, the team generates a long list of candidate opportunities, then applies a feasibility filter before scoring.
VPE Opportunity Matrix
| VALUE COMPONENT | EXAMPLE OPPORTUNITIES | FEASIBILITY CHECK | EXPECTED VPE SCORE |
|---|
| Functional (vfunc) | Consistent AI-generated deliverables; automated QA; zero-defect output pipelines | AI capability proven? Quality floor acceptable? | High if R improves materially |
| Outcome (vout) | Real-time ΔO dashboards for clients; AI-assisted performance attribution | Can you measure and attribute ΔO credibly? | High if β and ΔO are both large |
| Speed (vtime) | Same-day analysis that used to take a week; real-time reporting; instant drafts | Does faster delivery create real value for this customer? | Very high in time-critical sectors |
| Risk Reduction (vrisk) | Continuous compliance monitoring; anomaly detection; proactive alerts | Can you quantify Δpj · Lj for the client? | High in regulated industries |
| Information (vinfo) | Proprietary AI-generated market intelligence; benchmarking reports; signal synthesis | Is your data advantage defensible? | High if D (decision leverage) is high |
| Experience (vexp) | AI removes friction; humans focus on relationship; proactive service | Will customers perceive the improvement? | Medium — risk of depersonalization |
The VPE Score Equation
Each VPE opportunity k is scored using a simplified version of the value component equations:
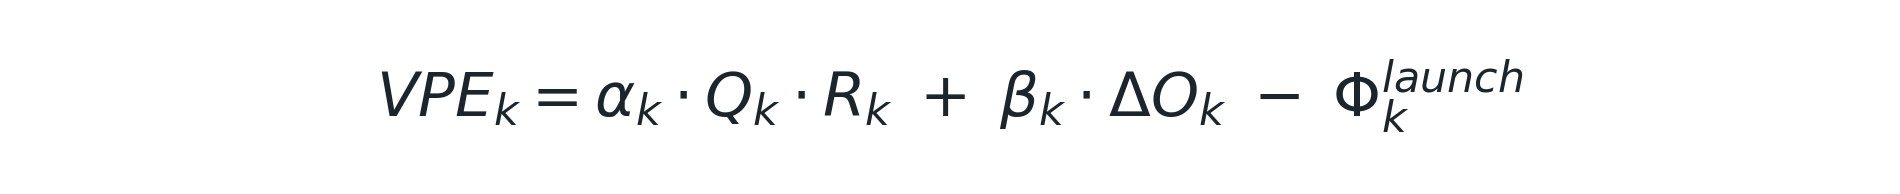
Where
VPEk
Value Prop Expansion Score for Opportunity k
The net estimated value delivered by VPE initiative k per customer per year, net of launch friction. This is the basis for ranking and selecting VPE investments. Higher scores represent more compelling expansion opportunities.
αk · Qk · Rk
Functional Value Component
The functional value of the new offering: the customer’s sensitivity to this type of output (αk) times the quality (Qk) and reliability (Rk) at which it can be delivered. Multiply these to test whether the offering is ready for market.
βk · ΔOk
Outcome Value Component
The outcome value of the new offering: the customer’s willingness to pay per unit of outcome improvement (βk) times the measurable outcome delta it delivers (ΔOk). Requires that you can measure and attribute the outcome.
Φklaunch
Launch Friction Cost
The total friction the customer must absorb to receive this new value: onboarding, learning, workflow adjustment, and trust calibration. High launch friction suppresses VPEk even when gross value is high. AI-assisted onboarding can reduce this term significantly.
Key Insight
The VPE cataloging phase typically generates 15–30 candidate opportunities across an organization. The VPEk score is the mechanism for narrowing this to a manageable investment portfolio. Rank all opportunities by VPEk score and take the top 5–8 into the portfolio optimization phase.
Phase 4 output
A long-list VPE catalog with a VPEk score for each opportunity, organized by value component. The top-scoring opportunities become the candidates for the Phase 5 portfolio ranking.
Phase 5: Optimize the AI Investment Portfolio
Select the Highest-Value Combination of Automation and VPE Initiatives Within Budget
With a ranked automation list (Phase 2) and a ranked VPE list (Phase 4), the question becomes: given a fixed budget for AI investment, which combination of initiatives maximizes the total value delivered? This is a portfolio optimization problem, and it has a formal mathematical structure.
The Portfolio Optimization Model
Let xk ∈ {0,1} indicate whether initiative k is selected (1) or not (0). The optimization problem is:
Where
xk
Initiative Selection Variable
A binary decision variable: 1 if initiative k is selected for investment in this planning cycle, 0 if not. The set of xk = 1 choices defines your AI investment portfolio for the year.
VPEk
Initiative Value Score
The VPEk score for VPE initiatives (from Phase 4) or the automation surplus AOVk for automation initiatives (from Phase 3). This is the objective value each initiative contributes when selected. Higher VPEk = more compelling to include.
Ck
Initiative Cost
The total investment required to implement initiative k: technology, implementation labor, change management, and training. This is the budget constraint input for each initiative.
B
Total AI Budget
The total capital and operating budget available for AI initiatives in this planning cycle. The constraint Σ xk · Ck ≤ B ensures the selected portfolio is feasible within approved resources.
In practice, this optimization can be solved with a simple spreadsheet using a greedy ranking approach: sort all initiatives by VPEk / Ck (value per dollar), then select in order until the budget is exhausted. For larger organizations with more complex interdependencies, linear programming tools or scenario modeling software can solve the exact integer program.
Calculating ROI Per Initiative
Before finalizing the portfolio, each selected initiative should have a validated ROI calculation:
Where
ROIk
Return on Investment for Initiative k
The net return on the AI investment in initiative k, expressed as a percentage of the investment cost. ROIk > 0 is the minimum bar; a portfolio-level IRR target (typically 30–60% for internal technology investments) should be the benchmark.
ΔΠk
Net Profit Change from Initiative k
The change in annual operating profit attributable to initiative k: revenue increase (ΔRk) minus cost change (ΔCk, which is negative for cost-reduction initiatives). This is the annual cash flow benefit of the investment.
Ckinvest
Investment Cost for Initiative k
The total capital and operating cost to implement initiative k. For a proper ROI calculation, this should include all one-time and ongoing costs over the payback period: technology licensing, implementation services, internal labor, and change management.
Key Insight
The portfolio optimization model treats automation initiatives and VPE initiatives as a unified investment decision. This is intentional: the highest-value AI strategies are those that pair automation (which liberates capacity) with VPE (which redeploys that capacity into revenue). A portfolio that is exclusively automation is a cost play. A portfolio that pairs automation with VPE is a growth play.
Phase 5 output
A finalized AI initiative portfolio for the planning cycle, with selected initiatives, total investment, projected ΔΠk for each, aggregate portfolio ROI, and a phased implementation calendar.
Phase 6: Make the Redeployment Decision Explicitly
Allocate Freed Capacity Between Margin Improvement and Growth
Every unit of labor capacity freed by automation must be allocated: to cost reduction (reducing headcount or avoiding new hires) or to value expansion (redeploying that capacity into VPE initiatives). This decision is the most consequential in the roadmap and the one most often made by default rather than by design.
The Mathematics of Work gives us the total capacity liberated by automation (the AOV calculation from Phase 3). The Mathematics of Value gives us the growth opportunities that capacity can fund (the VPE catalog from Phase 4). The redeployment decision is the bridge between them – and it has a precise mathematical condition that tells leaders which way to allocate each marginal unit of freed labor.
The Redeployment Condition

Where
α
Revenue Multiplier
The expected revenue generated per unit of labor capacity deployed into growth activities. Reflects market receptivity, competitive window, and the firm’s execution capability. Estimate this by modeling the revenue outcome of your top VPE initiatives relative to the labor they require.
R′(Lr)
Marginal Revenue from Redeployment
The marginal return on redeploying one additional unit of freed labor into growth. R′ is the derivative of the revenue function with respect to redeployed labor. Because R is concave, R′ declines as more labor is redeployed — the first units of redeployment are the most valuable.
β
Cost Capture Efficiency
The fraction of liberated labor cost that is actually captured as savings when capacity is reduced. Reflects severance costs, transition friction, and rehiring costs if volume rebounds. In most organizations, β is 0.6–0.8 rather than 1.0 — not all of the cost is recoverable.
C′(Lc)
Marginal Cost Savings from Reduction
The marginal savings from converting one additional unit of freed labor to headcount reduction. C′ is approximately constant (linear) in the short run, bounded by the fully loaded labor cost rate. It becomes the dominant option when R′ falls below (β/α) · C′.
The decision rule is: redeploy labor into growth activities (Lr) as long as the marginal revenue return exceeds the marginal cost saving. Convert to headcount reduction (Lc) when that inequality flips. Most firms should be running a portfolio across both Lr and Lc, calibrated to market conditions and execution bandwidth.
Key Insight
The most common error is to treat this as an either/or decision. It is not. The optimal allocation is a continuous split: redeploy as much as the market can absorb, and the organization can execute, and take the residual as cost savings. The mathematical condition tells you where the split point is.
Phase 6 output
An explicit redeployment plan showing total freed capacity (in FTE-equivalents and dollars), the Lr / Lc split decision for each function, and the specific VPE initiatives each redeployed unit will fund.
Phase 7: Track AI Maturity Continuously
Measure Where You Are on the Automation Spectrum Every Quarter
AI transformation is not a project with a completion date — it is a continuous process of moving tasks along the automation spectrum. Tracking your organization’s AI Maturity Index (AMI) gives leadership a single, comparable metric for how far the transformation has progressed and how fast it is moving.
The AI Maturity Index
Define the AI Maturity Index as the weighted average degree of automation across all tasks in the organization’s task register:
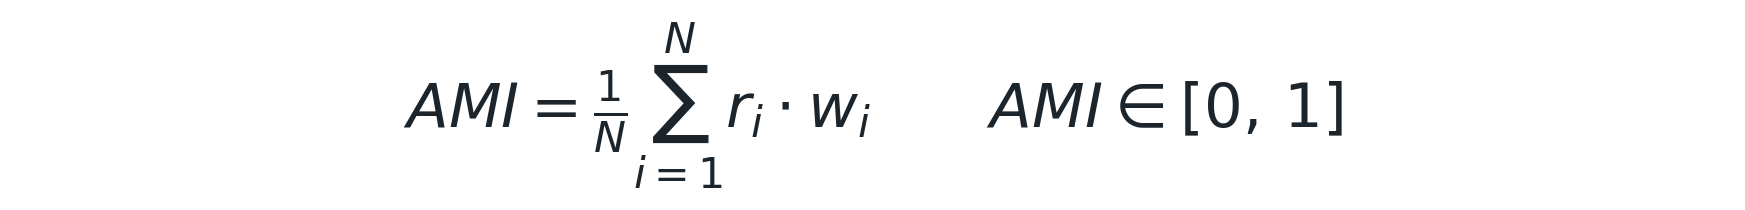
Where
AMI
AI Maturity Index
A single number in [0,1] representing the organization’s current average degree of AI augmentation across all tracked tasks. AMI = 0 is a fully human organization. AMI = 1 is a fully automated one. A mid-market professional services firm that has completed a meaningful AI transformation might target AMI = 0.45–0.60 within 24 months.
N
Total Number of Tasks
The total count of tasks in the organization’s task register. AMI is calculated across all N tasks, not just the automated ones, to ensure it reflects the full scope of the organization’s work.
ri
Degree of Automation per Task
The current degree of automation for task i, as defined in the continuous model. ri = 0 for fully human tasks, ri = 1 for fully automated. For human-in-the-loop tasks (copilot, AI-assisted), ri takes an intermediate value reflecting the AI contribution fraction.
wi
Task Importance Weight
The strategic importance weight of task i (from the weighted task model). Weighting by importance ensures that AMI reflects how much of the organization’s value-generating work is augmented, not just how many tasks have been touched by AI.
AMI should be calculated quarterly and tracked as a leading indicator of financial performance. As AMI rises, expect: Expense Index compression (cost savings), Revenue Index expansion (if freed capacity is being redeployed into VPE), and Valuation Multiple expansion (as investors recognize the operating leverage building in the business model).
Key Insight
AMI is most useful as a comparative metric: against your prior quarters, against your targets, and – where available – against competitors. A firm that grows AMI from 0.15 to 0.45 in 18 months while a competitor stays at 0.15 is building a structural cost and capability advantage that will compound.
Phase 7 output
A quarterly AMI dashboard by function and firm-wide, with trend lines, target trajectories, and comparisons to plan. This becomes a standing board-level reporting metric alongside revenue growth, margins, and client retention.
Phase 8: Monitor Net Firm Value Change
Close the Loop: Measure Whether AI Is Actually Building Firm Value
All of the preceding steps — task mapping, automation scoring, VPE cataloguing, portfolio optimization, redeployment, and maturity tracking — are means to a single end: increasing the long-run value of the firm. Phase 8 measures whether that is happening.
The Net Firm Value Model
The rate of change of firm value V as a function of the AI optimization program is modeled as:
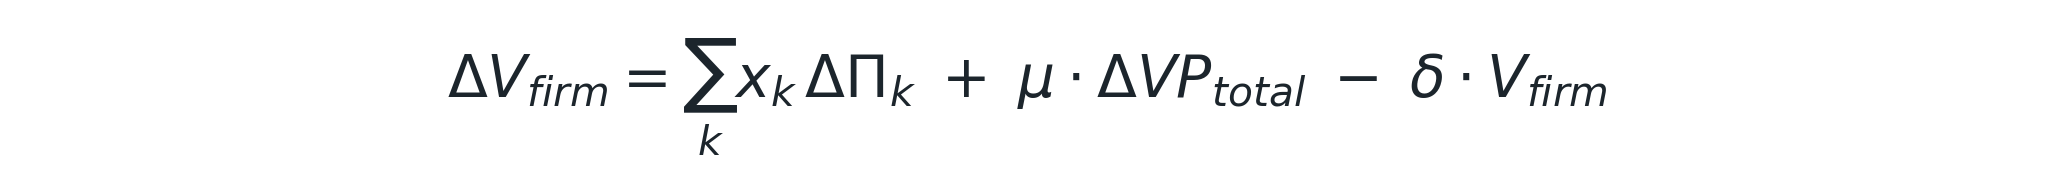
Where
ΔVfirm
Change in Firm Value from AI Program
The net change in enterprise value is attributable to the AI optimization program in each period. Positive ΔVfirm means the program is creating enterprise value faster than it decays. This is the ultimate scorecard metric.
Σ xkΔΠk
Sum of Profit Improvements
The total operating profit improvement from all selected AI initiatives (automation cost savings + VPE revenue increases), weighted by selection. This is the direct financial return of the portfolio.
μ · ΔVPtotal
Valuation Multiple Expansion
The additional enterprise value created by improvement in the total value proposition delivered to customers. μ is the revenue multiple relevant to the firm’s sector. As VPE initiatives succeed and customer value scores rise, μ·ΔVP translates into multiple expansion — the second-order valuation effect that early AI adopters will capture.
δ · Vfirm
Competitive Value Decay
The rate at which firm value erodes if competitors are advancing faster on their AI programs than you are. δ is the competitive decay rate — it is higher in rapidly automating sectors and lower in stable ones. This term is the mathematical expression of the cost of inaction.
The model makes an important and often-overlooked point: there is a competitive decay term, δ ·V, that erodes firm value independently of what the firm does. If competitors are automating faster, they are improving their Expense Index and expanding their value proposition while yours stays constant. The gap compounds. The model captures this: even a firm that invests nothing in AI loses value if δ > 0 in its sector.
Key Insight
The most powerful application of this model is not the calculation itself — it is the forcing function. When ΔVfirm is disaggregated into its components and reviewed quarterly, leadership can see exactly which initiatives are generating value, which are underperforming, and whether the competitive decay term is accelerating. That visibility drives better resource reallocation decisions than any amount of qualitative discussion.
Phase 8 output
A quarterly ΔVfirm model reconciliation: actual vs. projected profit improvement, VPE revenue contribution, AMI trend, and estimated competitive decay rate. This is the board-level AI accountability framework.
The Roadmap at a Glance
The eight phases form a closed-loop system. The outputs of each phase feed directly into the next. Phases 1–3 address the supply side of the business (how work is performed and at what cost). Phases 4–6 address the demand side (what value is delivered and how freed capacity is deployed). Phases 7–8 create the measurement infrastructure that keeps the system honest and improving over time.
| STEP | PHASE | KEY OUTPUT | MATHEMATICAL TOOL |
|---|
| 1 | Task Inventory | Complete task register with δi, ci, σi, ri scored | Task set J = {t1…tn} with attribute vectors |
| 2 | Automation Scoring | Priority-ranked automation list; Si score for each task | Task Value Score Si equation |
| 3 | Partition & Roadmap | TA vs. TH partition; 90-day pilot selection | Partition model T = TA ∪ TH; AOV calculation |
| 4 | VPE Cataloguing | Long list of value expansion opportunities by component | VPEk scoring across all 8 value dimensions |
| 5 | Portfolio Ranking | Prioritized VPE shortlist; investment case | Constrained portfolio optimization model |
| 6 | Redeployment Decision | Explicit Lr vs. Lc allocation for freed capacity | Labor redeployment differential equation |
| 7 | AI Maturity Tracking | AMI score; quarterly benchmark; trend | AMI = (1/N)Σ ri · wi |
| 8 | Value Monitoring | ΔVfirm vs. baseline; board-level reporting | Net firm value change model ΔVfirm |
“The firms that will define the competitive landscape of the next decade are not the ones with the largest AI budgets. They are the ones that systematically work through this process — mapping their tasks, quantifying their automation opportunities, cataloging where AI can expand what they deliver, and measuring whether it is happening.”
Where to Begin
Most business leaders who read this article will find it intellectually compelling but operationally daunting. The roadmap spans eight phases, eight equations, and substantial analytical work that must be completed before the first AI tool is deployed. That is the point.
The organizations that treat AI as a purchasing decision – evaluating vendors, signing contracts, and deploying tools – will get incremental improvements in the tasks those tools address. The organizations that treat AI as an analytical discipline – mapping their work, quantifying their opportunities, and optimizing their allocation of freed capacity – will build compounding structural advantages that accumulate over years, not quarters.
You do not need to complete all eight phases simultaneously. The 90-day starting point is Phase 1 and Phase 2: build the task register, compute the Si scores, and identify the top three automation pilots. Run those pilots rigorously, measure the outcomes, and use the results to calibrate your AOV model. That is enough to demonstrate proof of concept, build organizational confidence, and generate business cases for the full program.
The mathematics in this article and in previous articles are not prerequisites for starting. They are the tools that turn a good-faith effort into a defensible, optimized, and continuously improving system. Start with the task register. The equations will earn their place as the program matures.
If you are an executive or investor thinking through the organizational and strategic implications of AI for your business, we are always interested in those conversations. Reach out to the BIP Capital team directly.
© BIP Capital • This article reflects the views of BIP Capital’s Investment and Performance Engineering Team. It is intended for informational purposes and does not constitute investment advice.